Non-Sporting Societies and VAT
Article created 3 months ago
Updated about 3 months ago
Definition of Non-Sporting Groups
There are two types of student societies, and the VAT treatment differs for each type. The distinction lies in whether your group qualifies as a “sporting” group.
A “sporting” group is defined as one whose activities primarily involve physical activity, such as sports, dance, or fitness. A “non-sporting group” focuses on non-physical aims and objectives, which may include academic, cultural, political, or activist purposes.
To qualify as a sporting society, physical activity needs to be the group’s core purpose. Societies that offer sports membership alongside other activities will still be categorised as non-sporting and subject to taxation if their primary aim is not related to sports alone. This classification means that expenditure can still be recoverable for these societies. It's important to note that academic societies that organise sporting events may also face similar considerations in terms of VAT treatment.
The government, particularly HMRC, specifies which groups are considered “active” sporting groups and which are not.
If you would like to see our list of our active sporting groups, please click here.
VAT and Non-Sporting Groups
All non-sporting groups are subject to the standard rate of VAT, which is 20% on income from members (If you are unsure whether your group is a sporting society, you can check our list here).
This affects your group's income from:
- Membership Fees (For example, if your non-sporting society charges a £30 membership, the total VAT charge on each membership is £5 (20% of £30), meaning the society receives £25 of the payment)
- Activities related to core services
- Social events and activities
- Spectator admission charges (no exemptions for a non-sporting society)
- Stash sales
- Other Activities that are not VAT exempt
Non-sporting groups can, however, reclaim VAT on other costs where appropriate (more information on this can be found below).
As VAT is charged on this income, any VAT incurred on expenditure directly related to these taxable income streams may be reclaimed, subject to correct VAT documentation being provided. You must always ask for a VAT receipt or invoice with a VAT number when collecting evidence of your purchases. Without documentation, you will not be able to claim back VAT.
VAT within the Guild is complex due to our mix of business and non-business activities, and the Guild applies partial VAT recovery to certain overhead costs. However, this approach will not be extended to societies, as the administration involved is complex and resource-intensive. Therefore, VAT incurred on society overheads will be treated as non-recoverable and should be budgeted for as a cost.
VAT treatment for Income
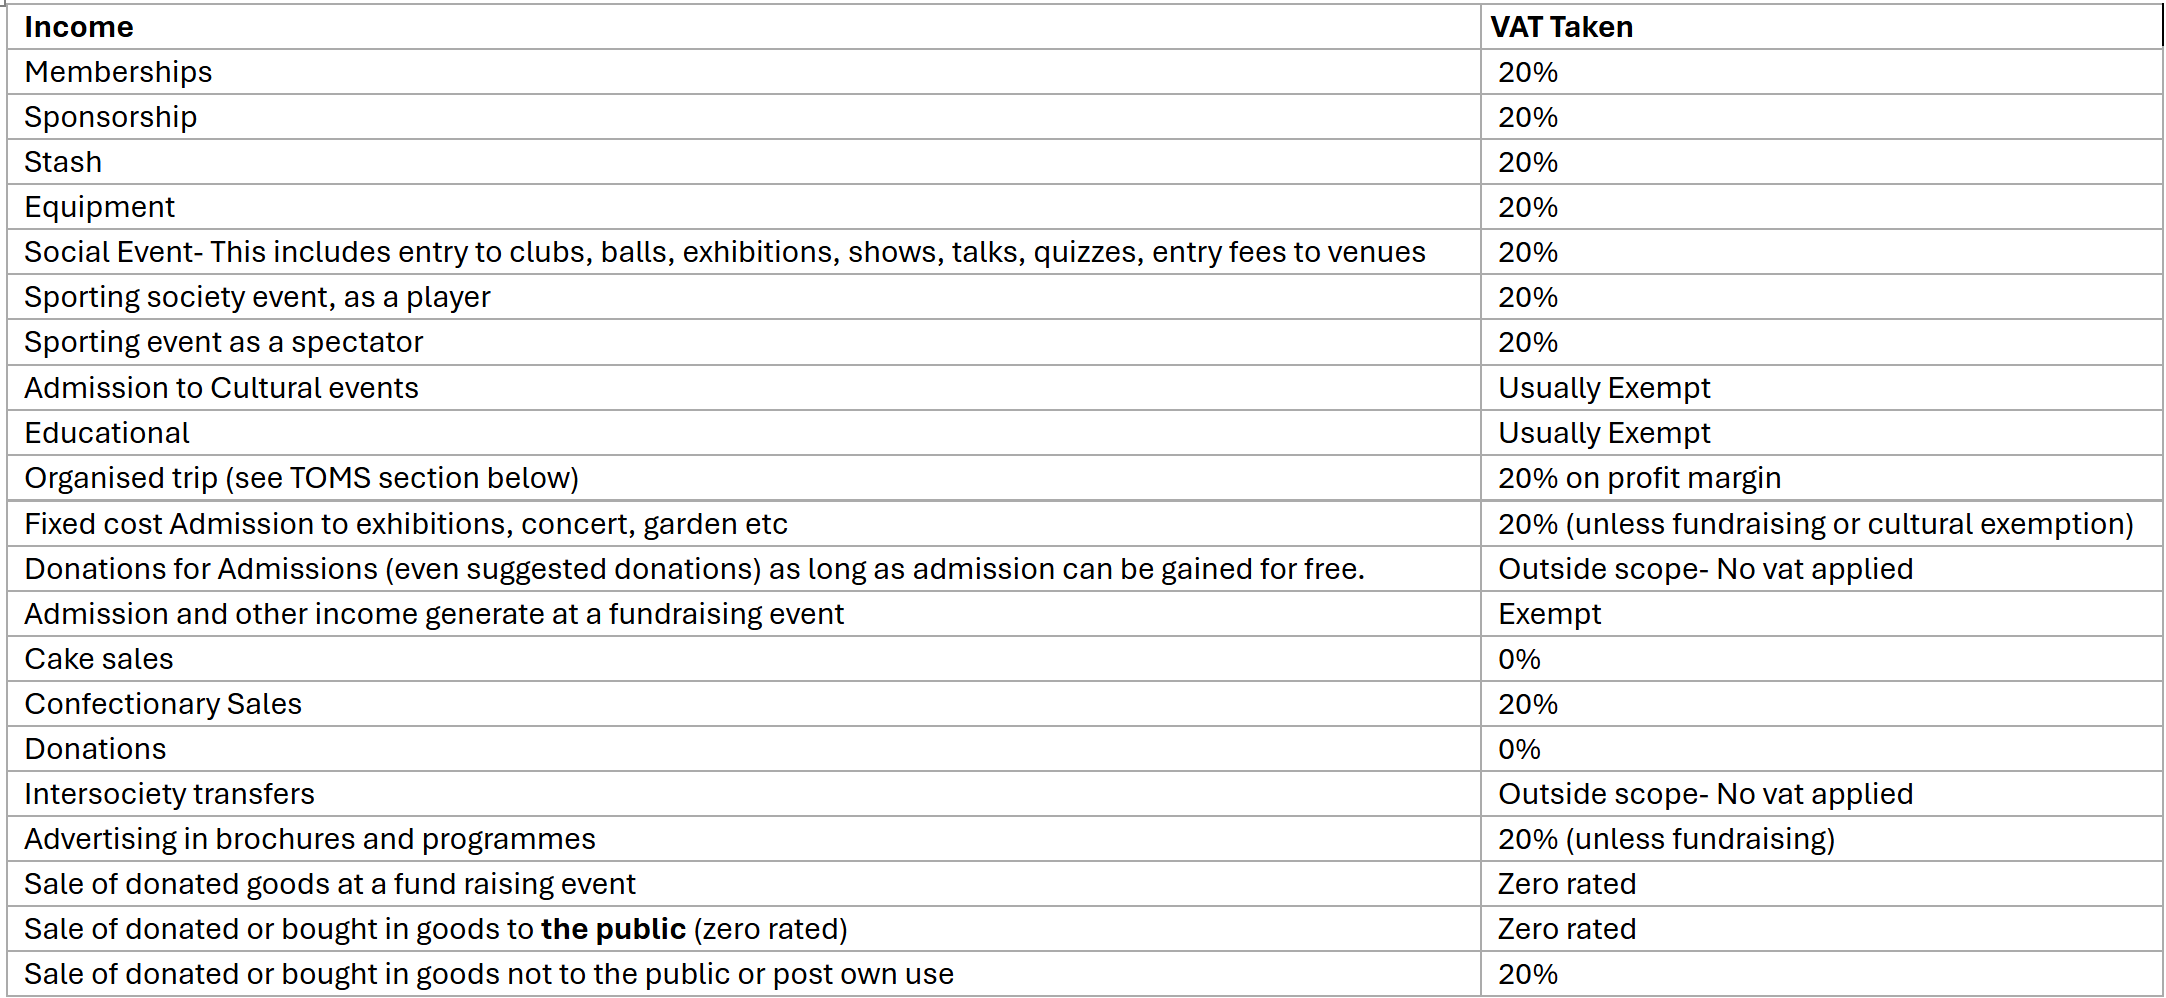
A big part of society activity is running events, socials, etc. These activities will generally be standard rated for VAT however, the society will also be able to recover VAT incurred on costs to run the event. There are some exemptions in HMRC VAT regulations which societies can benefit from.
If an activity is exempt, it means that VAT is not charged on the ticket sale, but also VAT incurred on costs cannot be recovered.
Exemption Categories are as follows:
- A sporting activity by a sporting society only
- An event that also provides transport, ticket admission, accommodation as part of the ticket price
- A Cultural event
- A fundraising event
- An educational event
The following table shows you the treatment of income streams for VAT purposes for your society:
VAT and Donations
If your group secures any donations or grants, these will be VAT free so your group will receive the full amount.
VAT treatment for Expenditure
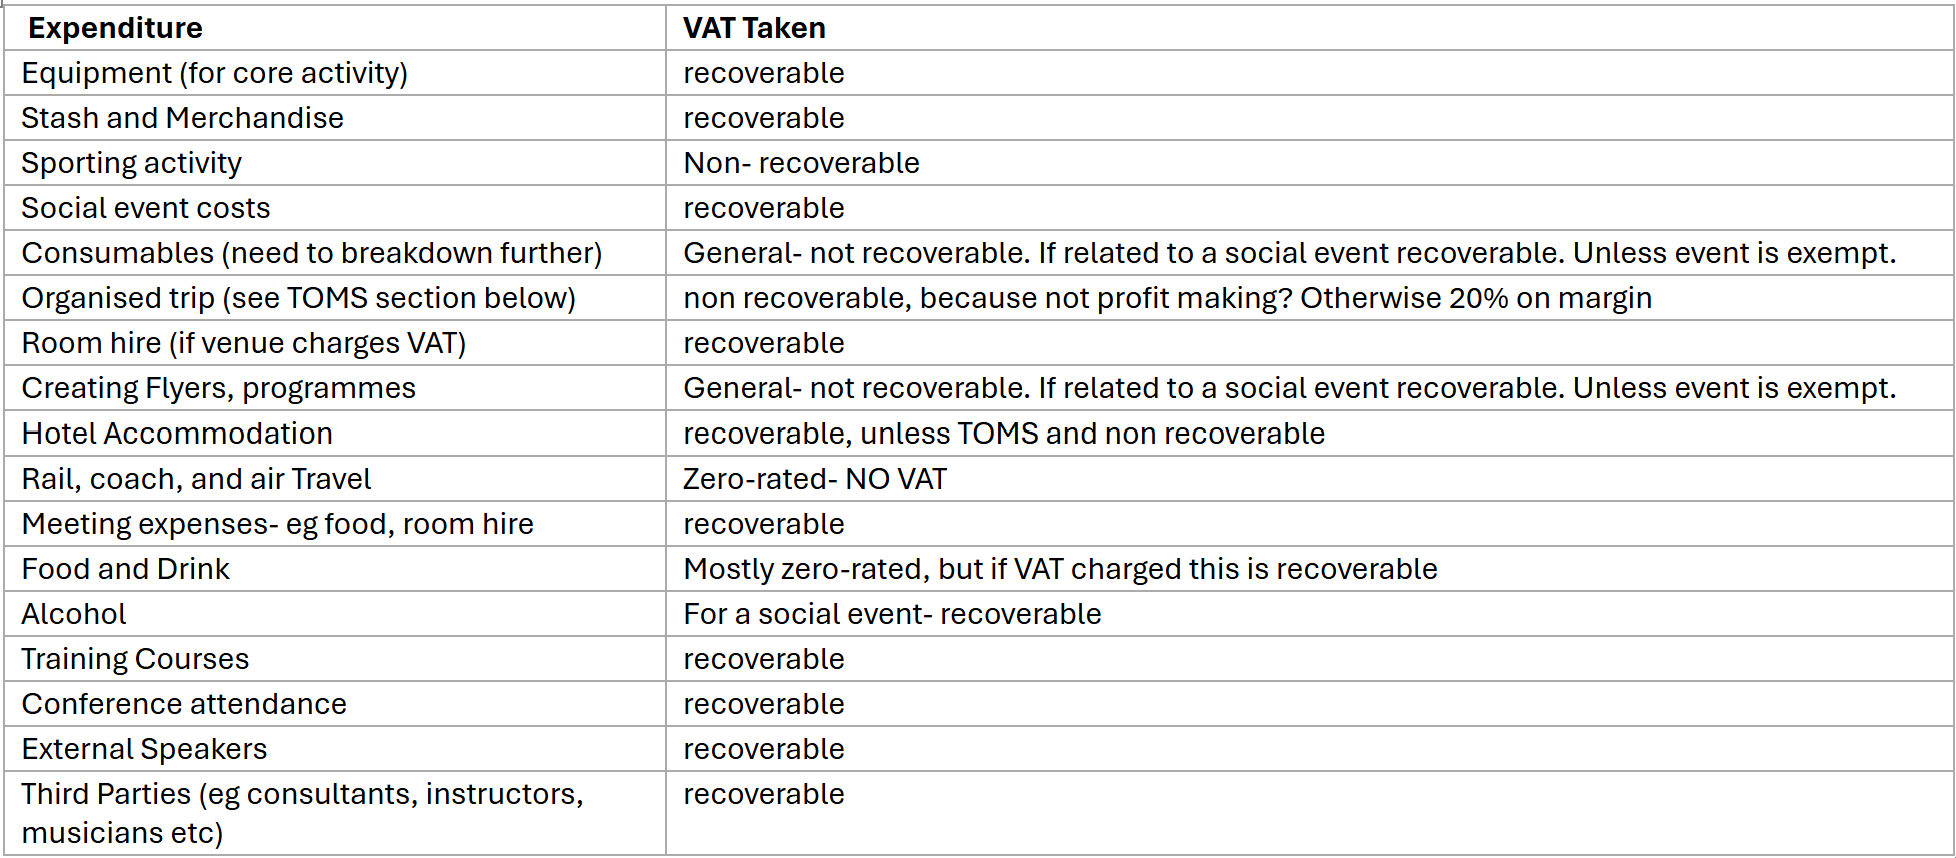
If VAT is charged on income, VAT incurred on expenditure directly related to this taxable income stream may be reclaimed, subject to correct VAT documentation being provided. VAT cannot be reclaimed on exempt activities. Some suppliers do not issue VAT invoices/receipts as standard and you will have to request them- such as restaurants, supermarkets, online purchases (amazon purchases).
The following table shows the treatment of types of expenditure for VAT purposes:
VAT is not recoverable on the following costs:
Why? These items are classed as overheads, which fall into the partial exemption rules. We do not have the capacity to review every claim and establish what VAT rules apply. It is therefore prudent to treat as non-recoverable. These types of costs are likely to be minimal.
- Office Supplies (stationery, printer ink, postage supplies
- IT equipment
- Software Subscriptions
- Marketing
- Advertising- creating and displaying an advert
- Photocopying
- Printing
- Agency Fees
- Website Hosting
- Promotional merchanise/freebies
- Gifts to members (small amounts, e.g. leaving or thank you gesture)
Need Help?
If you can't find the answers you're looking for in any of our articles, you can get in touch with us by using our help system.
If you are a committee member, you should use the Help and Support solution in the committee portal or alternatively contact us via email at activities@exeterguild.com.